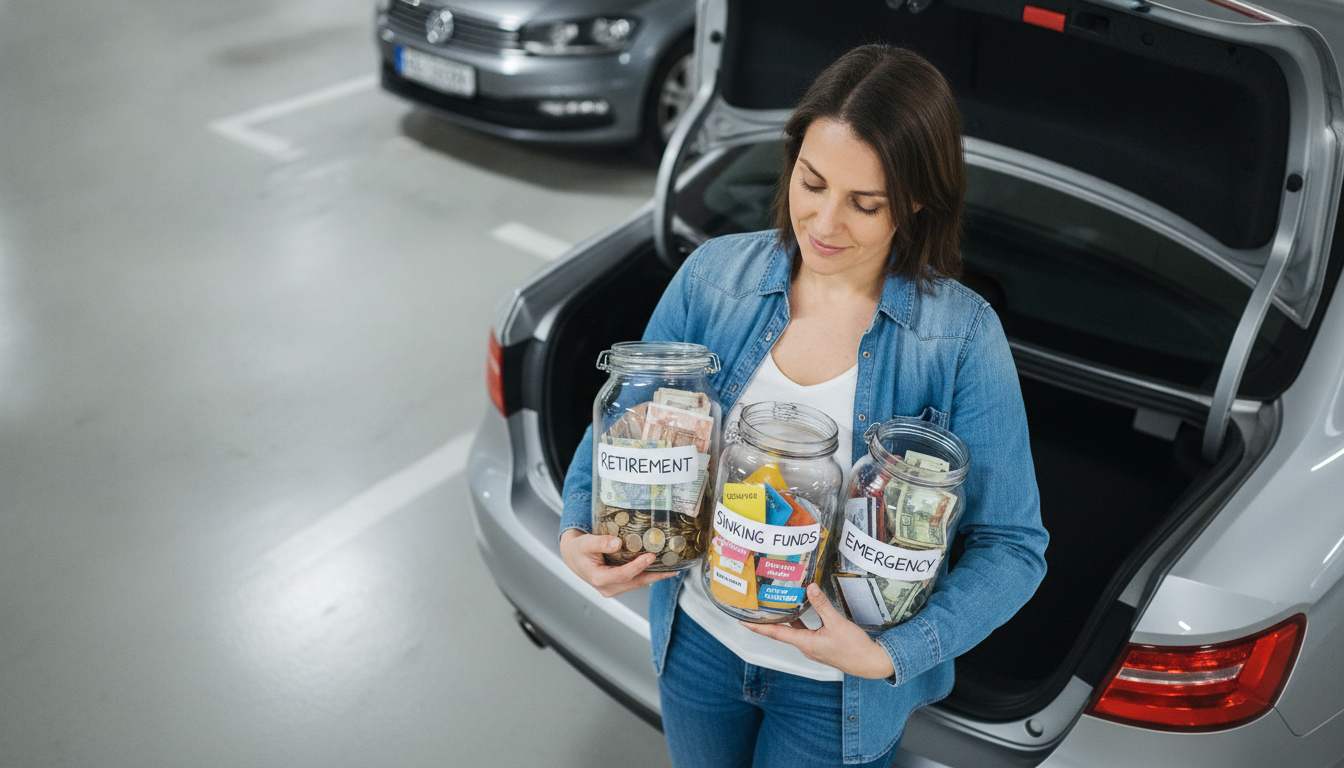
Good savings goals are clear, time-based targets that match real-life priorities and make progress easy to measure. The best goals typically cover protection (so a surprise bill doesn’t derail you), upcoming planned expenses, and long-term wealth building. Instead of saving “more,” aim for specific dollar amounts and deadlines you can track each month.
A common benchmark is 3–6 months of essential expenses (housing, utilities, food, insurance, minimum debt payments). If that number feels too big, start with a starter goal like $500–$1,000, then scale up. Keep this money accessible in a high-yield savings account so it’s there when you need it.
Sinking funds are savings buckets for expenses you know are coming, such as car repairs, holidays, back-to-school shopping, annual insurance premiums, or vet bills. Good goals here are based on estimates: set a total amount and divide it by the months until the due date to get a realistic monthly target.
If you regularly finance purchases, set savings goals to pay cash instead—like replacing a phone, upgrading a laptop, or refreshing home essentials. Choose a deadline and automate a weekly transfer so the purchase doesn’t compete with monthly bills.
If an employer offers a retirement match, a strong goal is contributing enough to capture the full match, since it’s essentially extra pay. After that, consider increasing contributions gradually (for example, by 1% every few months) so it doesn’t feel disruptive.
Milestones like a wedding, moving costs, a down payment, or a dream trip become manageable when you break them into smaller checkpoints. Set a target amount, a date, and a monthly contribution—then review progress quarterly and adjust as needed.
For more examples and a deeper breakdown of how to pick targets that fit your budget, visit https://perfectpickspalace.shop/what-are-good-savings-goals/.
A solid starting point is 10% to 20% of take-home pay, but the best number is the one you can sustain. If that’s too high right now, begin with a smaller fixed amount and increase it after raises or when expenses drop.





Leave a comment